Fitch affirms Romanian Romgaz at BBB-/negative
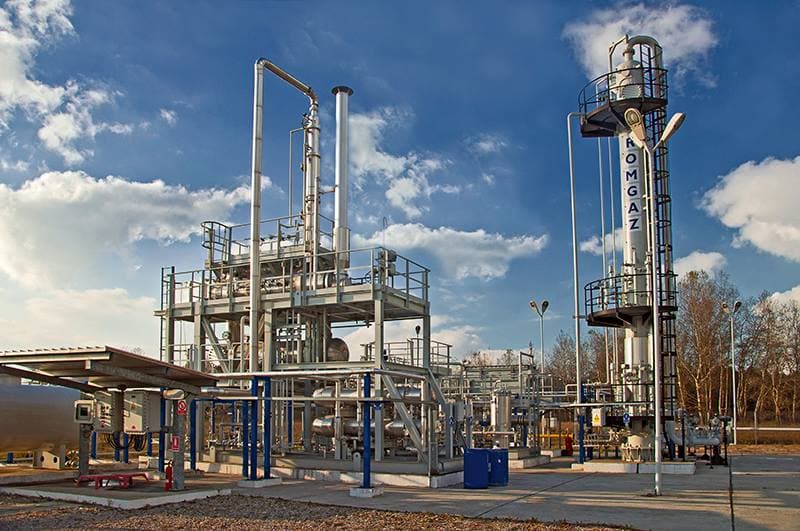
Fitch Ratings has affirmed the long-term issuer default rating (IDR) of Romania-based Romgaz (BVB: SNG) at the level of BBB- with a negative outlook.
iulian ernst · Journalist
· 2 min read
The negative outlook reflects the outlook on Romania's sovereign rating.
Romgaz's BBB- rating benefits from a one-notch uplift from its bb+ standalone credit profile (SCP) for state support, under the rating agency’s Government-Related Entities (GRE) Rating Criteria.
Among the key rating drivers is the good progress made in the Neptun Deep offshore gas project.
Neptun Deep has achieved major milestones in 2026: the Neptun Alpha production platform was installed in the Black Sea in July 2026, the 160-km export pipeline to Tuzla is complete, and seven of 10 development wells have been drilled, the rating agency said.
Romgaz and OMV Petrom will complete the remaining Domino field wells, install subsea infrastructure and umbilicals, finish the Tuzla metering station, and conduct testing and commissioning. First gas remains on track for 2027, with plateau production of about 8 bcm/year.
Steady progress with development of the project is positive for Romgaz's credit profile.
Fitch sees the Neptun Deep project as a transformational project for Romgaz. It will allow Romgaz to increase natural gas production to about 160 thousand barrels of oil equivalent per day (mboe/d) from 86 mboe/d in 2025, halting a stable to declining production trend from existing mature reservoirs.
The project will also secure Romania's energy independence and position the country as the EU's largest natural gas producer from domestic resources. It views execution risk as manageable, given the partner's experience in oil and gas project development.
Another key rating driver is the Iernut gas-fired power plant, which approaches completion. Romgaz is making advances in the construction of the Iernut combined-cycle gas turbine (CCGT) power plant after considerable delay, which it expects will start production in 1Q27.
Romgaz will benefit from sales of electricity on the balancing market, which it expects to increase in importance as renewable electricity generation rises with its inherent output volatility. The addition of electricity sales EBITDA from 2027 will improve the company's business diversification, although upstream activity will remain the dominant cash flow contributor.
A key driver with a negative impact on Romgaz is the regulated gas price. The Romanian government implemented regulations to protect consumers in the gas supply market, in response to the Russia-Ukraine war. A majority of Romgaz's gas sales is at regulated prices, which amounted to RON 120 per megawatt hour (MWh) from April 2024 to March 2026. The capped price was reduced to RON 110/MWh from April 2026.
Sales at these regulated prices are exempt from windfall taxes, and royalties are based on capped prices. Current regulation extends till end-March 2027.
Free newsletters
Romania, in your inbox before your first coffee.
Get the Daily — the morning briefing, free, in English, unsubscribe anytime. Want business, real estate or travel digests too? Pick your newsletters →